Helping you move forward with confidence

Serving clients in BC from my office in Cranbrook.
GET STARTED

Finding the best mortgage can be frustrating. It doesn't have to be when you follow my 3 step plan.

Get started right away

The best place to start is to connect with me directly. My commitment is to listen to your needs, assess your financial situation, provide professional mortgage advice, and guide you through the mortgage process.

Get clarity

Sorting through all the different mortgage lenders, rates, terms, and features can be overwhelming. Let me cut through the noise. I'll outline the best mortgage products available with your needs in mind.

Proceed with confidence

My goal is to make sure you know exactly where you stand at all times. From your initial application through your mortgage renewal, I'm available to answer any questions for as long as you need a mortgage. I've got you covered.
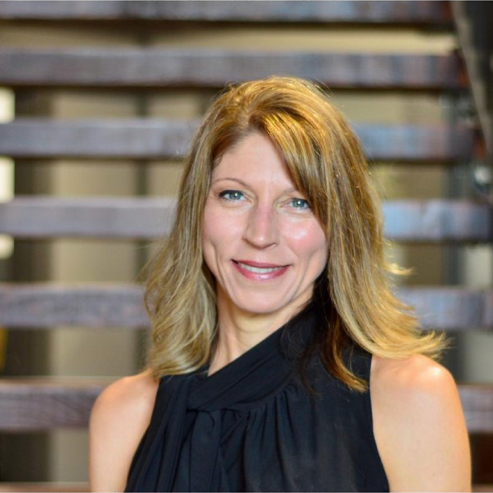
Hi, I’m Debra Sluz (formerly Debra Parker), Mortgage Broker, and I’m passionate about helping my clients find the right mortgage solution for their unique needs.


I’ve been in the mortgage industry since 2006, and prior to that, I spent 12 years as an Assistant Manager with a consumer finance company. That experience gave me a strong foundation in working with a wide range of clients—including those who may not fit the traditional mold—and allows me to confidently guide you through every step of the mortgage process.


As your mortgage professional, I work for you—not the bank—giving you access to a wide range of lenders and mortgage products so you can feel confident you’re getting the very best solution for your goals. My approach is built on clear communication, personalized advice, and consistent support, helping you move forward with confidence and momentum.

To me, arranging your mortgage is just the beginning of our relationship. I stay connected with my clients to ensure you continue to have the right mortgage strategy in place—whether you’re renewing, refinancing, or planning your next move—so you can keep building momentum toward your financial goals.


I was raised in the Kootenays and have spent most of my life here, so I truly understand our local market and community. Outside of work, I enjoy travelling, spending time with friends and family, and staying active.


I’m an avid cyclist and have been fortunate to achieve several athletic milestones, including setting a Canadian Powerlifting Record in Bench Press (2006). More recently, I was proud to be named Canadian National Time Trial Champion (50–54) in 2024, and in 2025, both the Canadian National Time Trial and Road Race Champion (50–54)—as well as earning 3rd place at the UCI World Championships in Lorne, Australia.

If you’re looking for a mortgage experience that is simple, strategic, and designed to keep you moving forward, it would be my pleasure to help

Nice things people have said about working with me.

Everything you need, all in one place

As a trusted mortgage provider, let me help you with these services.

Click through any of the services to learn more
Canadian Mortgage Experts has partnered with APOLLO, Canada’s leading online provider of personal & business insurance, to provide exclusive home and condo insurance offers.
LEARN MORE

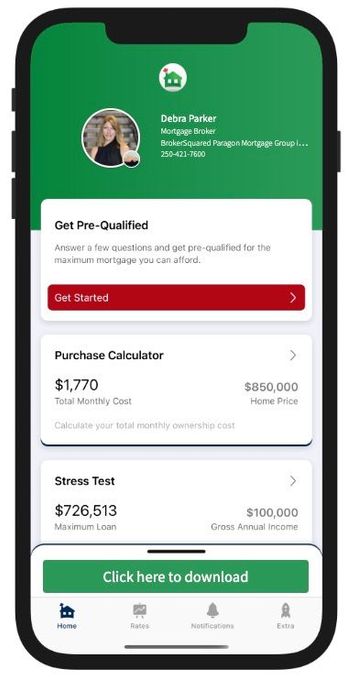
Download my Canadian Mortgage App

What you can do with my app


Calculate your total cost of owning a home

Estimate the minimum down payment you need

Calculate Land transfer taxes and the available rebates

Calculate the maximum loan you can borrow

Stress test your mortgage

Estimate your Closing costs

Compare your options side by side

Search for the best mortgage rates

Email Summary reports (PDF)

Use my app in English, French, Spanish, Hindi, and Chinese
DOWNLOAD APP

Get started by completing my online mortgage application.

APPLY NOW

I'll let you know exactly where you stand so you can proceed with confidence.

Go ahead and schedule a meeting with me!


Mortgage articles to keep you informed.

By Debra Sluz (Formerly Parker) September 10, 2026
Why a Mortgage Pre-Approval Protects Both Your Head and Your Heart There’s no denying it—buying a home is an emotional journey. In a competitive market, it can feel like you need to stretch beyond your comfort zone or bid above asking just to have a chance. That pressure can make it hard to separate what you want from what you can realistically afford. One of the biggest pitfalls buyers face is falling in love with a home that’s outside their price range. Once that happens, every other property seems like a compromise—even the ones that might have been a perfect fit otherwise. The best way to avoid this heartache? Get pre-approved before you start shopping. What a Pre-Approval Does for You A mortgage pre-approval gives you more than just a number—it provides clarity, confidence, and protection: Know your buying power : Shop within your true price range and avoid disappointment. Spot potential roadblocks : Uncover issues like credit bureau errors before you make an offer. Get organized : Learn exactly what documentation you’ll need so there are no surprises. Lock in a rate : Many lenders hold your rate for 30–120 days, giving you peace of mind if rates rise. Save yourself heartache : Protect yourself from falling for a home you can’t afford. Head vs. Heart Buying a home is about balance. Your head tells you what’s financially sound, your heart tells you what feels right—and both matter. A pre-approval helps bring those two sides together, so you can make confident choices without emotional stress clouding your judgment. The Bottom Line Looking at properties for fun is one thing—but if you’re serious about buying, a pre-approval is the smartest first step you can take. It sets realistic expectations, saves time, and protects your emotions along the way. If you’d like to explore your options and get pre-approved, I’d be happy to walk through the process with you. Let’s make sure you’re ready to shop with confidence.
By Debra Sluz September 2, 2026
The Bank of Canada announced today that it is holding its target for the overnight rate at 2.25%, with the Bank Rate at 2.5% and the deposit rate at 2.20%. While Canada's economic recovery is broadening, a new layer of uncertainty has entered the picture. Here is what happened and what it means for your mortgage.
By Debra Sluz (Formerly Parker) September 1, 2026
Don’t Forget About Closing Costs When planning to buy a home, most people focus on saving for the down payment. But the truth is, that’s only part of the equation. To actually finalize the purchase, you’ll also need to budget for closing costs —the out-of-pocket expenses that come up before you get the keys. Closing costs can add up quickly, which is why they should be part of your pre-approval conversation right from the start. Lenders will even require proof that you’ve got enough funds set aside. For example, if you’re getting an insured (high-ratio) mortgage, you’ll need at least 1.5% of the purchase price available in addition to your down payment. That means a 10% down payment actually requires 11.5% of the purchase price in cash to make everything work. Let’s break down some of the most common expenses you should prepare for: 1. Home Inspection & Appraisal Inspection : Paid by you, this gives peace of mind that the property is in good shape and doesn’t have hidden problems. Appraisal : Required by the lender to confirm value. Sometimes this is covered by mortgage insurance, sometimes by you. 2. Legal Fees A lawyer or notary is required to handle the title transfer and make sure the mortgage is properly registered. Legal fees are often one of the larger closing costs—unless you’re also responsible for property transfer tax. 3. Taxes Many provinces charge a property or land transfer tax based on the home’s purchase price. These fees can range from hundreds to thousands of dollars, so you’ll want to factor them in early. 4. Insurance Property insurance is mandatory—lenders won’t release funds without proof that the home is insured on closing day. Optional coverage like mortgage life, disability, or critical illness insurance may also be worth considering depending on your financial plan. 5. Moving Costs Whether you’re renting a truck, hiring movers, or bribing friends with pizza and gas money, moving comes with expenses. Cross-country moves especially can be surprisingly pricey. 6. Utilities & Deposits Setting up new services (electricity, water, internet) can involve connection fees or deposits, particularly if you don’t already have a payment history with the utility provider. Plan Ahead, Stress Less This list covers the big-ticket items, but every purchase is unique. That’s why it pays to have an accurate estimate of your personal closing costs before you make an offer. If you’d like help planning ahead—or want a breakdown tailored to your situation—let’s connect. I’d be happy to walk you through the numbers and make sure you’re fully prepared.
By Debra Sluz (Formerly Parker) September 10, 2026
Why a Mortgage Pre-Approval Protects Both Your Head and Your Heart There’s no denying it—buying a home is an emotional journey. In a competitive market, it can feel like you need to stretch beyond your comfort zone or bid above asking just to have a chance. That pressure can make it hard to separate what you want from what you can realistically afford. One of the biggest pitfalls buyers face is falling in love with a home that’s outside their price range. Once that happens, every other property seems like a compromise—even the ones that might have been a perfect fit otherwise. The best way to avoid this heartache? Get pre-approved before you start shopping. What a Pre-Approval Does for You A mortgage pre-approval gives you more than just a number—it provides clarity, confidence, and protection: Know your buying power : Shop within your true price range and avoid disappointment. Spot potential roadblocks : Uncover issues like credit bureau errors before you make an offer. Get organized : Learn exactly what documentation you’ll need so there are no surprises. Lock in a rate : Many lenders hold your rate for 30–120 days, giving you peace of mind if rates rise. Save yourself heartache : Protect yourself from falling for a home you can’t afford. Head vs. Heart Buying a home is about balance. Your head tells you what’s financially sound, your heart tells you what feels right—and both matter. A pre-approval helps bring those two sides together, so you can make confident choices without emotional stress clouding your judgment. The Bottom Line Looking at properties for fun is one thing—but if you’re serious about buying, a pre-approval is the smartest first step you can take. It sets realistic expectations, saves time, and protects your emotions along the way. If you’d like to explore your options and get pre-approved, I’d be happy to walk through the process with you. Let’s make sure you’re ready to shop with confidence.
By Debra Sluz September 2, 2026
The Bank of Canada announced today that it is holding its target for the overnight rate at 2.25%, with the Bank Rate at 2.5% and the deposit rate at 2.20%. While Canada's economic recovery is broadening, a new layer of uncertainty has entered the picture. Here is what happened and what it means for your mortgage.
By Debra Sluz (Formerly Parker) September 1, 2026
Don’t Forget About Closing Costs When planning to buy a home, most people focus on saving for the down payment. But the truth is, that’s only part of the equation. To actually finalize the purchase, you’ll also need to budget for closing costs —the out-of-pocket expenses that come up before you get the keys. Closing costs can add up quickly, which is why they should be part of your pre-approval conversation right from the start. Lenders will even require proof that you’ve got enough funds set aside. For example, if you’re getting an insured (high-ratio) mortgage, you’ll need at least 1.5% of the purchase price available in addition to your down payment. That means a 10% down payment actually requires 11.5% of the purchase price in cash to make everything work. Let’s break down some of the most common expenses you should prepare for: 1. Home Inspection & Appraisal Inspection : Paid by you, this gives peace of mind that the property is in good shape and doesn’t have hidden problems. Appraisal : Required by the lender to confirm value. Sometimes this is covered by mortgage insurance, sometimes by you. 2. Legal Fees A lawyer or notary is required to handle the title transfer and make sure the mortgage is properly registered. Legal fees are often one of the larger closing costs—unless you’re also responsible for property transfer tax. 3. Taxes Many provinces charge a property or land transfer tax based on the home’s purchase price. These fees can range from hundreds to thousands of dollars, so you’ll want to factor them in early. 4. Insurance Property insurance is mandatory—lenders won’t release funds without proof that the home is insured on closing day. Optional coverage like mortgage life, disability, or critical illness insurance may also be worth considering depending on your financial plan. 5. Moving Costs Whether you’re renting a truck, hiring movers, or bribing friends with pizza and gas money, moving comes with expenses. Cross-country moves especially can be surprisingly pricey. 6. Utilities & Deposits Setting up new services (electricity, water, internet) can involve connection fees or deposits, particularly if you don’t already have a payment history with the utility provider. Plan Ahead, Stress Less This list covers the big-ticket items, but every purchase is unique. That’s why it pays to have an accurate estimate of your personal closing costs before you make an offer. If you’d like help planning ahead—or want a breakdown tailored to your situation—let’s connect. I’d be happy to walk you through the numbers and make sure you’re fully prepared.
Show More